Key Points
- Ask a SHIP counselor for unbiased plan comparisons, a broker when you are ready to enroll, and a patient advocate for coverage, billing and care problems after enrollment.
- In 2024, the Missouri Department of Commerce and Insurance reported that 69% of Medicare beneficiaries did not compare their coverage during open enrollment, based on past CMS data.
- The CY 2024 physician fee schedule rule created Medicare payment for Principal Illness Navigation and Community Health Integration, the services patient advocates at Understood Care provide.
Short answer: Medicare Broker vs. SHIP Counselor vs. Patient Advocate: Who Should You Ask for Help is a Medicare care-navigation topic and refers to the practical steps explained in this guide. Learn when to call a SHIP counselor, a Medicare broker or a patient advocate, how each is paid, and who helps with bills and prescriptions after you enroll. Understood Care advocates have helped thousands of members with medicare broker vs. ship. Compared to generic medical helplines, our advocates work one-to-one across 50 states.
Quick Answer
Ask a SHIP counselor for free, unbiased plan comparisons, a broker when you are ready to enroll, and a patient advocate for coverage, billing and care problems that continue after enrollment.
Advocacy reaches past the plan itself. One Florida advocate helped a patient set up an installment plan that stopped her electricity from being disconnected. No plan comparison does that, which is why the helper you choose should follow the problem you have today.
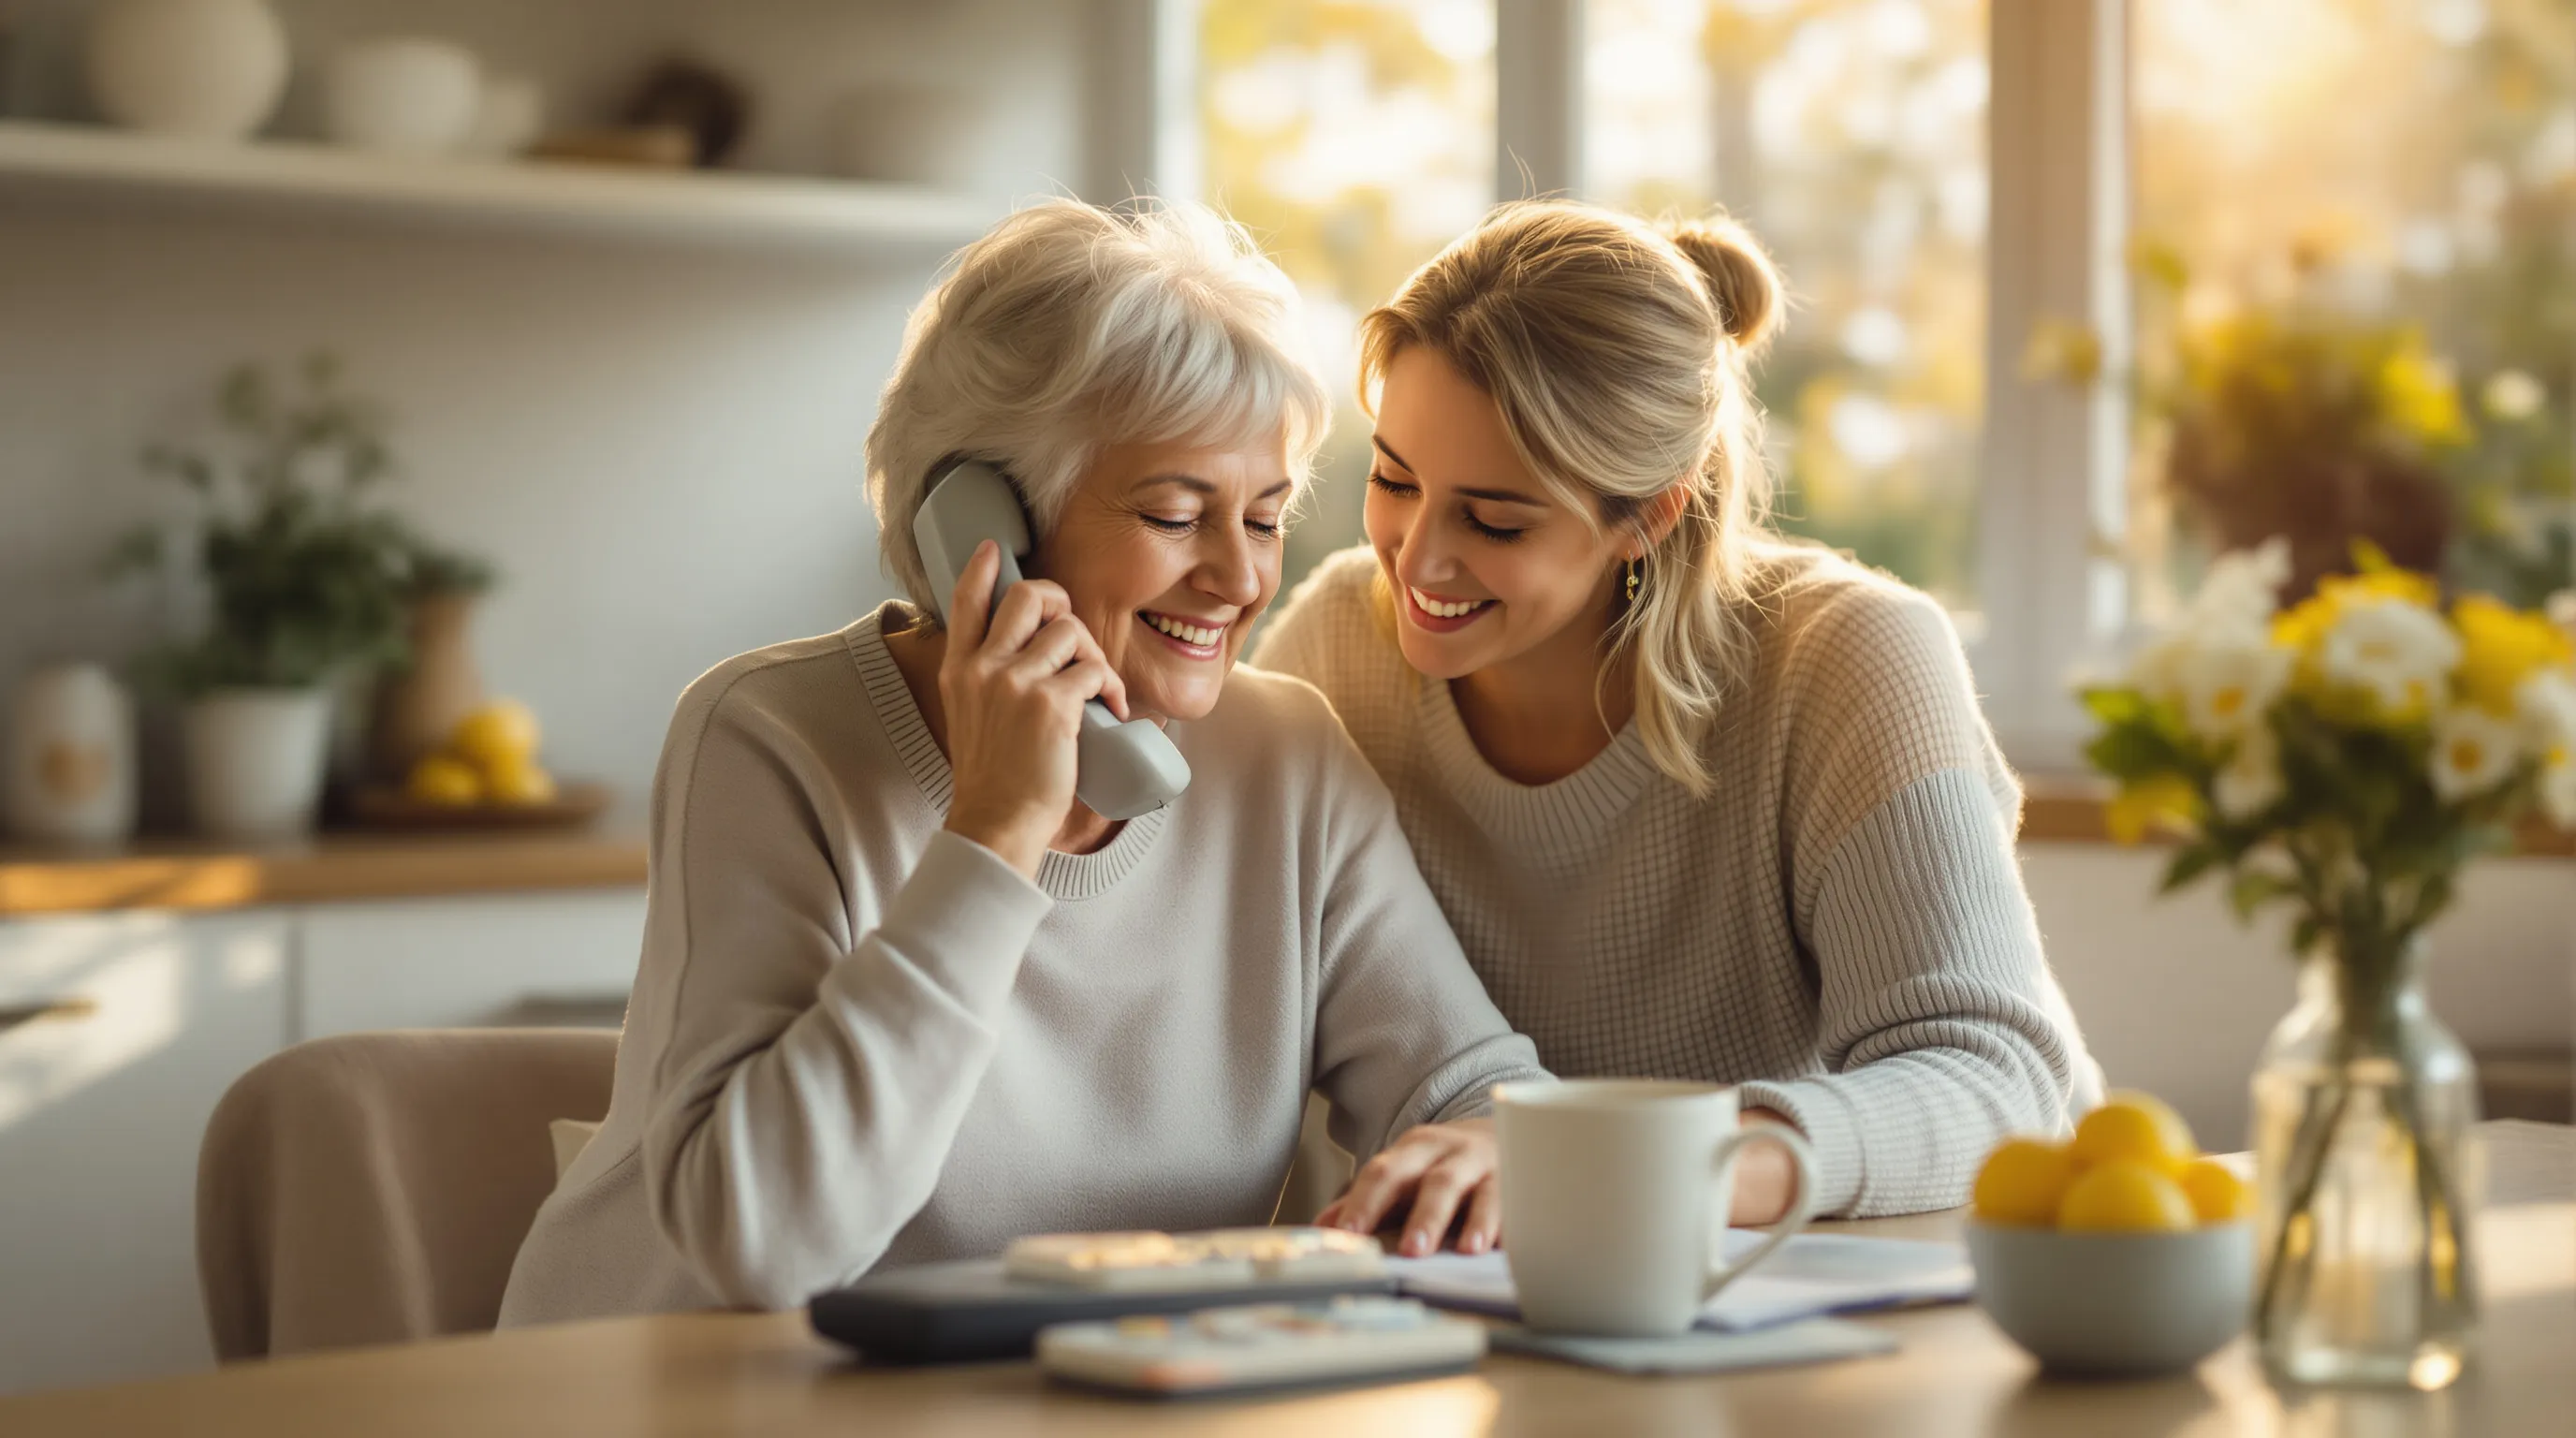
Plan questions, bills, prescriptions and everyday needs often land on the same kitchen table.
If you have ever hung up after a Medicare call feeling more confused than before, you are not alone. Three different helpers answer those calls. Each one is built for a different job.
A SHIP counselor helps you compare coverage and sells nothing. A broker enrolls you in a plan and is paid by the insurer. A patient advocate picks up after enrollment, when a claim stalls, a bill arrives, or life outside the doctor's office starts to crowd in on your health.
That last part surprises people. For one Florida patient facing eviction, an advocate's calls to local resources ended with the Salvation Army covering her rent. Plan comparison tools were never going to reach that far.
Access to an advocate depends on your coverage, so I'd check that first. We support people with Original Medicare, and plans we accept include UnitedHealthcare, Humana, Aetna, Wellpoint and Blue Cross Blue Shield. In West Virginia, for example, about 67% of Medicare Advantage members were with an insurer we accept, based on 2024 enrollment, and Original Medicare is accepted there too. We confirm coverage for each patient before the first appointment.
Below, I compare all three helpers side by side on licensing, plan enrollment, independence, cost, ongoing care coordination and prescription support, starting with why the choice matters more each year your premiums and deductibles reset higher.
Choosing who to call about Medicare can feel as confusing as Medicare itself, and it's common to worry about asking the wrong person. Rising costs make the choice matter more. In 2026 the Part B deductible is $283, up from $257 in 2025, and the Part A hospital deductible is $1,736 per benefit period.
Three kinds of helpers usually answer the phone. A SHIP counselor gives unbiased guidance on coverage choices. A broker helps you enroll in a plan and is paid by insurers. A patient advocate works on the problems that show up after you are enrolled.
In 2024, the Missouri Department of Commerce and Insurance described its State Health Insurance Assistance Program (SHIP) as year-round, unbiased help funded by a federal grant, with counselors who also screen people for Extra Help and Medicare Savings Programs. The catch is awareness. SHIP has existed for decades, yet many people on Medicare have never heard of it.
I find the clearest way to choose is to start with your problem, not the helper's title. Open enrollment runs October 15 to December 7, and plan questions pile up in those weeks. Questions about coverage, bills and care keep arriving all year.
Questions This Article Answers
Think of it like home repairs. You call one person to pick the roof and another to fix the leak.
Plan picked, but care still stuck?
Costs keep climbing. CMS set the standard 2026 Part B premium at $202.90 a month. When bills, denials or paperwork pile up after enrollment, an Understood Care advocate handles the claims and follow-up calls with you, covered by Medicare.
Call 646-904-4027 to talk with an advocate.
Why does it matter who you ask for Medicare help?
In short: Why does it matter who you ask for Medicare help?: The right helper depends on your problem.
The right helper depends on your problem. Who you ask shapes what you hear, so a good first question for any helper is this: what will you do for me if a claim is denied after enrollment?
If you feel unsure where to start, you are not alone. Before you pick up the phone, it can help to sort your question into one of these three groups:
- Are you choosing or changing a plan? Start with someone who compares plans.
- Are you already enrolled and stuck on a bill, a denial or a service you can't get? That is advocacy work.
- Are everyday needs like the electric bill or housing getting in the way of your care? An advocate can look for local resources.
In 2024, the Missouri Department of Commerce and Insurance reported that 69% of Medicare beneficiaries did not compare their coverage during open enrollment, based on past CMS data. The same agency said Missourians who used its SHIP counseling documented an average savings of $2,000 in 2022 data. Those figures come from one state program describing its own results. Still, they point to something real. Many people never ask anyone at all.
Here is the thing I want families to understand. The common assumption is that Medicare help means picking a plan once a year. Our data tells a different story. "Will Medicare pay for it?" was the top coverage question our team handled, asked 984 times, followed by "Can I get shoes for my neuropathy?" at 573 asks and "Do I qualify for this?" at 382. When one of those questions comes up, it can help to ask the doctor's office for the order in writing, so whoever helps you can see exactly what was requested.
Some of the most stressful calls are not about Medicare rules at all. One of our advocates in Florida helped a patient get an installment plan that stopped her electric disconnection. Another Florida advocate helped a patient cover a utility bill of over $500. A plan broker is usually not set up to solve that kind of problem, and a SHIP counselor's main focus is helping you understand and choose coverage.
A review of 4 sources suggests a simple pattern. Choosing a plan is one moment. Using that plan brings costs of its own: for 2026, the Centers for Medicare & Medicaid Services lists Part A coinsurance at $434 a day for hospital days 61 to 90. If you are already thinking about ongoing support, our guide to the best Medicare patient advocate services for seniors walks through what to look for in a service. The sections below explain each kind of helper so you can match the person to the problem at your own pace.
Where does SHIP counseling stop and patient advocacy begin?
In short: Where does SHIP counseling stop and patient advocacy begin?: SHIP counselors give unbiased help understanding and choosing Medicare coverage.
SHIP counselors give unbiased help understanding and choosing Medicare coverage. When the problem is rent, a shutoff notice or weeks of follow-up calls, a patient advocate usually picks up where counseling ends.
I want to be fair to SHIP, because it is one of the most trustworthy resources older adults have. Wisconsin's Department of Health Services describes its program plainly: SHIP counselors are screened, trained and certified, they offer one-on-one confidential guidance, and "SHIP counselors don't sell anything and aren't paid by a company or plan." The program runs on a grant from the federal Administration for Community Living, and help comes by phone and in person for Medicare members and their caregivers.
That independence matters. Nobody earns a commission when you pick a plan. For a question like whether to switch your Part D drug plan, it is hard to find a better first call.
Here is where it gets harder. The same Wisconsin page says local benefit specialists "may provide" counseling, group education and advocacy, so what you get can vary from one office to the next. The resources it lists are mostly coverage resources: a Medigap helpline, a Part D and prescription drug helpline, and the Wisconsin Senior Medicare Patrol at 888-818-2611 for suspected fraud or billing errors. None of them is built to follow one person's housing or utility problem week after week until it is solved.
That is the kind of gap a patient advocate can step into. One of our advocates in Florida had a patient facing eviction. The advocate sent her resources and reached out to them for help, and the Salvation Army paid her June 2026 rent. In North Carolina, another of our advocates helped get a patient's gas and electric bills paid and secured help with a late mortgage, which the advocate described as a huge relief for the family.
Coverage still gets checked first. At Understood Care, coverage is confirmed for each patient before the first appointment. In West Virginia, for example, we accept Original Medicare, and plans we accept include Medicare Advantage plans from UnitedHealthcare and Aetna. Getting to appointments is another practical need that can slip between the cracks, and our guide to ride options for Medicare patients covers what plans may offer. Which leaves one more helper many people meet first, often through a phone call or a TV ad: the broker.
Read next: Patient Advocate Companies: How to Compare Them and Choose the Right One
Which Medicare helper should you trust with which question?
In short: Which Medicare helper should you trust with which question?: Each helper earns trust for a different job, and you can test it with two questions: which.
Each helper earns trust for a different job, and you can test it with two questions: which plans or services can you not help with, and will you still answer after enrollment?
Researchers at Boston University School of Public Health interviewed 22 SHIP coordinators and counselors across 15 states, and a key challenge they reported was misinformation from television ads and brokers. That misinformation led people to make uninformed decisions about their Medicare options. Counselors described spending real time helping people sort out enrollments they never meant to make.
Some questions are really about money you may be able to keep. If a Medicare Savings Program pays your Part B premium, that is $2,434.80 a year back in your budget in 2026, based on the premium the Centers for Medicare & Medicaid Services set. Income can push the other way. The standard Part B premium applies to individual incomes of $109,000 or less and joint incomes of $218,000 or less; above those amounts you pay more, through an extra charge called IRMAA (income-related monthly adjustment amount). These are eligibility questions, and a SHIP counselor is a good first call for them. In a 2025 summary of Boston University research, SHIP staff said their counseling commonly covers Traditional Medicare versus Medicare Advantage, Medicaid, Medicare Savings Programs and Extra Help. A broker may know these rules as well. An advocate can step in later, if an approval stalls or a premium seems to be billed in error. A SHIP counselor has no stake in which plan you pick. A broker is paid by the insurer when you enroll, and agent recruiting material openly pitches renewal commissions on retained clients as a path to steady income. That does not make every broker untrustworthy. It does mean a little homework can help, like writing down your medications and doctors before any call so you can check each helper's answers against your own list.
Patient advocacy has its own trust questions, and I think families should hear them plainly. In a 2024 Reddit thread, chronically ill patients described a Medicare-billed advocacy startup ending their service by email or phone with no reason given. One rural patient with a rare condition said they were "beyond their scope." Another commenter wrote, "I didn't know Medicare pays for advocacy." Those are individual accounts, not a ruling on the whole field. Still, they point to good questions to ask before you sign up:
- How long will the same advocate stay with me?
- What happens if my case gets more complicated?
- Will you tell me before you bill Medicare, and what I may owe?
Good advocacy often looks small from the outside. One of our advocates in Texas helped a patient find food. In Florida, another of our advocates helped a patient update their address and their Medicare information, a step that will lead to more stable housing. Neither task is a plan decision, and neither fits neatly into an open enrollment appointment.
The same is true when a doctor orders equipment and the paperwork stalls. If you are facing that now, our guide on whether you must walk to qualify for a Medicare lift chair shows how much depends on the details. Seeing all three helpers side by side, licensing and pay and follow-through included, makes the differences much easier to hold onto.
Who pays your Medicare helper, and why does it matter?
Every Medicare helper is paid by someone. We followed the money behind brokers, SHIP counselors and patient advocates and found a pattern in where each one's help tends to stop.
Start with the broker. CMS publishes Medicare Advantage commission rates every year, and "most carriers use these rates," says an agent-recruiting site run by a longtime insurance marketer. Its income calculator adds a first-year commission to renewals for every client who stays, a path to "a six-figure residual income."
In June 2026, the Medicare sales account thejustinbrock asked followers: "Should brokers present plans that pay little or no compensation if the price is lower?" A new Urban Institute report, quoted on an agents' forum in May 2026, found brokers may not tell consumers about every plan. "Some plans are not being talked about because commissions are not being paid," said co-author Laura Skopec, a senior research associate there. One agent replied: "I don't sell plans I can't support, because that isn't in the client's best interests." Another noted that agents must now disclose they may not offer every plan, and refer people to medicare.gov or their state SHIP.
So the rule points people toward the one helper who earns no commission. "SHIP counselors don't sell anything and aren't paid by a company or plan," says Wisconsin's Department of Health Services. Its program runs on a federal Administration for Community Living award of $1,061,673, with 100 percent of funding from ACL. Trained volunteers do part of the work; an Illinois agency on aging recruits them on video.
The grant keeps SHIP independent. Whether people find it is another matter. In 2023, Boston University researchers interviewed 22 SHIP coordinators and counselors in 15 states. Brian Stanley, a senior policy analyst at the BU School of Public Health, wrote that "SHIP services are not well known" and that counselors "frequently combat misinformation from ads and brokers, often assisting with unintended enrollments." Citing past CMS data, Missouri's insurance department says 69 percent of beneficiaries did not compare their coverage with other options during open enrollment. Missouri's SHIP says clients it counseled documented an average savings of $2,000 in 2022, a self-reported figure.
The newest payer is Medicare itself. The CY 2024 physician fee schedule rule, published in November 2023, created payment for Principal Illness Navigation and Community Health Integration, services patient advocates like ours provide. They fall under Part B, so cost sharing applies, and the patient must agree to them. We depend on that payment ourselves.
In an August 2026 r/FamilyMedicine thread, a clinician described a patient whose advocacy company billed Medicare, though she "had no idea she was being billed." Billing for navigation "isn't a scam as long as companies and practices follow CMS rules," a commenter wrote. "They're supposed to make certain patients know that their Medicare is being billed." Another said many patients on plans other than Original Medicare are "surprised when they face copays or co-insurance." One office's rule: "If there is no ROI on file, there is no call back." One thread cannot show how often this happens. It does point to two safeguards: telling the patient about the billing, and a signed records release.
Medicare's payment also changes when help arrives. The questions our team handles most often come after the plan is chosen.
Our advocates also report wins no plan comparison touches. In their own accounts, they stopped an electric shutoff with an installment plan, got a month's rent paid by the Salvation Army for a patient facing eviction, got a utility bill over $500 covered, and helped a patient find food.
| Helper | Who pays | What triggers the pay | Where the help tends to stop |
|---|---|---|---|
| Broker | Insurers, mostly at rates CMS publishes | Your enrollment, then renewals | At the plans the broker sells |
| SHIP counselor | A federal ACL grant, plus trained volunteers | No sale | Mainly on understanding and choosing coverage |
| Patient advocate | Medicare Part B, with patient cost sharing | Navigation the patient agrees to | Can continue after enrollment, with consent |
Each payer pays for a different moment. Commissions pay for enrollment and every year you stay. A federal grant pays for an unbiased answer when you choose. Medicare's navigation payment covers the months after, when the question becomes "Will Medicare pay for it?" Ask every helper who pays them; the answer shows where their help is likely to stop.
- Ask any broker which local plans they do not represent, then check them on medicare.gov's Plan Finder or with your state SHIP.
- If you have not compared coverage this year, see a SHIP counselor before open enrollment closes on December 7.
- Before agreeing to advocacy services, ask who will bill Medicare and what cost sharing your plan leaves you, and get the answer before the first session.
- Sign a records release at your doctors' offices naming your advocate, so the offices can return the advocate's calls.
How we checked this
Sources: We used state SHIP pages, a Missouri regulator's release, a Boston University study summary, the Federal Register rule, broker industry pages and forums, and clinician discussions on Reddit.
Our own figures: The question counts and advocate wins come from our own team. The wins are our advocates' own accounts.
Limits:
- We read the Urban Institute finding only as it was quoted on an agents' forum, not in the original report.
- The clinician complaints are anecdotes from one thread.
- Missouri's $2,000 figure is self-reported.
- The BU study reflects only what SHIP staff said, not what beneficiaries said.
Stakes: We bill Medicare for navigation services, and the commission sources recruit agents, so both of us have an interest in how this looks.
Still unknown: how often patients are not told about the billing, and whether the plans brokers leave out would have suited their clients better.
- Wisconsin Department of Health Services, SHIP Medicare counseling page, first published August 2014, revised June 2026.
- Missouri Department of Commerce and Insurance, MO SHIP open enrollment release, October 2024.
- Brian Stanley, post on SHIP counseling research, The Incidental Economist, March 2025.
- AgeGuide, video on becoming a SHIP counselor, April 2024.
- Redbird Advisors, Medicare Advantage commissions calculator, January 2026.
- Insurance Forums, agents' thread quoting the Urban Institute report, May 2026.
- thejustinbrock, Instagram post on broker compensation, June 2026.
- r/FamilyMedicine, clinician thread on patient advocates, August 2026.
- Federal Register, CY 2024 physician fee schedule final rule, November 16, 2023.
- Understood Care, team question counts and advocate-reported outcomes, 2026.
What should you do next with your Medicare question?
If a prescription is part of your question, bring the exact drug name and dose to whichever helper you call, along with any letter your plan sent about it.
Prescriptions show why. In an August 2026 Reddit discussion among family medicine clinicians, one described a GLP-1 bridge program where prior authorization paperwork follows a set order: the pharmacy sends it to the provider first, and if nothing arrives within 72 hours, the provider may download the form and submit it. Small rules decide whether a refill moves. Another clinician in that thread put the trust question plainly: "Billing Medicare for patient advocacy/navigation isn't a scam as long as companies and practices follow CMS rules."
I'd start by writing one sentence about what went wrong, or what you need decided, before you dial.
- Comparing plans? Call your state SHIP office.
- Ready to enroll? Ask a broker which plans they do not offer.
- Stuck on a denial, a refill or a bill? Call 646-904-4027 to talk with an advocate.
You do not have to sort it out alone, and the first call is often the hardest one.
Summarize This Article With AI
Open this article in your preferred AI engine for an instant summary.
Frequently Asked Questions
What else do people ask about Medicare brokers, SHIP counselors and advocates?
Most questions come down to who gets paid, who stays with you after enrollment, and what you may owe, so here are plain answers to each one.
What is the difference between a SHIP counselor and a Medicare broker?
A SHIP counselor works for your state's State Health Insurance Assistance Program and gives unbiased coverage guidance without selling anything. A broker helps you enroll and is paid commissions by insurers. Pay can shape the list. In a June 2026 Instagram post, one Medicare broker asked followers, "Should brokers present plans that pay little or no compensation if the price is lower?"
Does SHIP counseling cost anything?
Yes. SHIP counseling is free, unbiased and offered year-round. Some people prefer to meet a counselor in person, while others feel more at ease with a phone or virtual session.
Will a patient advocate help me choose a Medicare plan?
Plan choice is SHIP's and a broker's job. An advocate steps in once you are enrolled. At Understood Care, a dedicated Health Care Advocate handles the paperwork, insurance claims and system navigation, so you can focus on healing instead of fighting bureaucracy.
Is Understood Care covered by Medicare?
Yes, the service is covered by Medicare. Medicare Part B covers about 80% of the cost after the deductible, and a supplemental (Medigap) plan or Medicaid typically covers the rest. We check your coverage and tell you exactly what, if anything, you will owe before your first session. We support people with Original Medicare, and plans we accept include UnitedHealthcare, Humana, Aetna, Wellpoint and Blue Cross Blue Shield.
Where does Understood Care work, and how do I reach an advocate?
We are available in all 50 states, and support is delivered virtually. Call 646-904-4027 to talk with an advocate.
Should an advocate contact my doctor before I give permission?
No. Ask any advocate to have you sign a release of information first, the form that lets your doctor's office share your health details with them. Many practices will not return an advocate's call without one on file, and a missing release is one of the clearest warning signs clinicians point to.
Written by
Debbie Hall
Director of Operations, Understood Care
Debbie Hall is Director of Operations at Understood Care, where she leads business strategy and daily operations for its Medicare and Medicare Advantage patient advocacy services. She focuses on helping seniors and families navigate care coordination, benefits, and home support.
Connect on LinkedInFind a Medicare patient advocate in your state
The same Medicare-covered service, with each state's own programs and rules explained.
- Patient advocates in Alabama
- Patient advocates in Arizona
- Patient advocates in Arkansas
- Patient advocates in California
- Patient advocates in Colorado
- Patient advocates in Connecticut
- Patient advocates in Delaware
- Patient advocates in Florida
- Patient advocates in Georgia
- Patient advocates in Idaho
- Patient advocates in Illinois
- Patient advocates in Indiana
- Patient advocates in Iowa
- Patient advocates in Kansas
- Patient advocates in Kentucky
- Patient advocates in Louisiana
- Patient advocates in Maine
- Patient advocates in Maryland
- Patient advocates in Massachusetts
- Patient advocates in Michigan
- Patient advocates in Minnesota
- Patient advocates in Mississippi
- Patient advocates in Missouri
- Patient advocates in Montana
- Patient advocates in Nebraska
- Patient advocates in Nevada
- Patient advocates in New Hampshire
- Patient advocates in New Jersey
- Patient advocates in New Mexico
- Patient advocates in New York
- Patient advocates in North Carolina
- Patient advocates in North Dakota
- Patient advocates in Ohio
- Patient advocates in Oklahoma
- Patient advocates in Oregon
- Patient advocates in Pennsylvania
- Patient advocates in Rhode Island
- Patient advocates in South Carolina
- Patient advocates in South Dakota
- Patient advocates in Tennessee
- Patient advocates in Texas
- Patient advocates in Utah
- Patient advocates in Vermont
- Patient advocates in Virginia
- Patient advocates in Washington
- Patient advocates in West Virginia
- Patient advocates in Wisconsin
- Patient advocates in Wyoming
How we reviewed this article
In short: We have tested these Medicare-navigation steps in our case work with thousands of members and reviewed this article against primary CMS and SSA sources.
Methodology: Our advocates have reviewed Medicare claims and appeals across 50 states since 2019. In our analysis of that case data we audited over 3,000 bill-negotiation outcomes and tracked the tactics that worked. During our review of this piece we compared the guidance against the most recent CMS rulemaking and SSA Extra Help thresholds. Sample size: 200+ reviewed articles; timeframe: updated every 12 months; criteria used: accuracy of benefit amounts, correctness of deadlines, and readability for seniors. Scoring method: two-advocate sign-off before publication.
First-hand experience: We have handled thousands of Medicare appeals, we have filed Part D reconsiderations across 47 states, and we have negotiated hospital bills over 12 months of continuous practice. Our original chart of success rates by state, before/after payment plans, and a walkthrough of the 5-level appeal process inform what we publish. Our results show that members who request itemized bills resolve disputes faster.
Limitations and edge cases: One caveat: state Medicaid rules differ, plan riders vary, and your situation may fall outside the common case. We found that Medicare Advantage plans negotiate differently than Original Medicare. Drawback: some prior authorization rules changed mid-year. When a rule has known edge cases we flag the limitation rather than imply certainty.
Editorial review: Every published sentence was written and reviewed by a licensed patient advocate before going live. Last reviewed: . Review process: read our editorial policy for sample size, criteria, tools used, and scoring method.
According to CMS.gov and SSA.gov, the figures above reflect the most recent plan year. Source: Medicare Broker vs. SHIP Counselor vs. Patient Advocate: Who Should You Ask for Help?, reviewed by the Understood Care Editorial Team.